

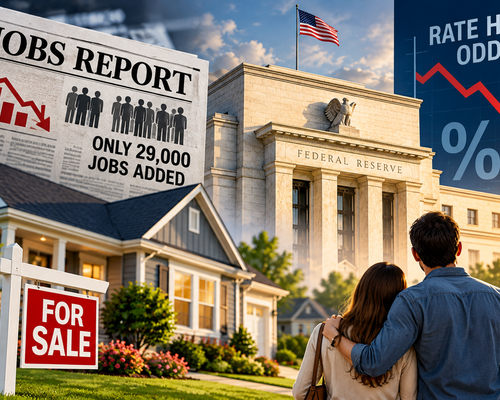
A weakening U.S. labor market may have given the housing market something it desperately needs: less pressure on the Federal Reserve to keep raising interest rates.
The U.S. economy added just 29,000 jobs in September, while the unemployment rate edged up to 4.2%, according to the latest report from the Bureau of Labor Statistics. Payroll growth for July and August was also revised lower by a combined 60,000 jobs, painting a weaker picture of the labor market heading into the final quarter of the year.
The report comes at a critical time for housing. Mortgage rates climbed sharply through September, with the average 30-year fixed rate moving above 7% as investors reacted to inflation concerns, energy prices and expectations for Federal Reserve policy.
A softer labor market could now change that equation.
The Fed Has More Reason to Wait
The Federal Reserve raised its benchmark interest-rate target by a quarter percentage point at its September meeting, bringing the range to 3.75% to 4%. The move marked the first rate increase since 2023.
But monetary policy is increasingly complicated by a labor market that is losing momentum.
The Fed has been balancing two competing risks: inflation that remains above its long-term target and employment that is showing signs of weakening. A prolonged deterioration in hiring could make another rate increase more difficult to justify, particularly if policymakers become more concerned about economic growth.
That does not mean a rate cut is suddenly guaranteed. Energy prices and inflation remain important obstacles, and the Fed has made clear that future decisions will depend on incoming economic data.
Still, the September jobs report gives policymakers another reason to pause and evaluate the impact of the rate increases already delivered.
What It Could Mean for Mortgage Rates
Mortgage rates do not move directly with the federal funds rate. Instead, they are heavily influenced by longer-term Treasury yields and investor expectations about inflation and economic growth.
That means a weaker economy can sometimes help mortgage rates even before the Fed changes its policy rate.
NAR Chief Economist Lawrence Yun said the latest employment data could provide some relief for mortgage rates following their sharp September increase. If investors begin to expect slower economic growth and less aggressive Fed policy, Treasury yields could come under downward pressure, potentially giving mortgage rates room to retreat.
For buyers, even a modest decline could make a meaningful difference in monthly payments and purchasing power.
Housing Still Has a Long Way to Go
The problem is that one weak jobs report does not solve the housing market's affordability problem.
Home prices remain elevated in many parts of the country, while mortgage rates are still significantly higher than they were during the pandemic-era housing boom. Buyers are gaining leverage as inventory improves, but many households remain unable or unwilling to take on today's monthly payments.
The latest labor-market numbers could therefore represent an important turning point rather than an immediate solution.
If employment continues to weaken while inflation gradually cools, the Fed could have more flexibility to stop raising rates. That would give financial markets more room to price in lower borrowing costs and potentially take some pressure off mortgage rates.
For now, the housing market is watching the jobs data just as closely as the next inflation report. A sustained slowdown in hiring could ultimately become one of the clearest reasons for the Fed to step back from further rate increases, giving homebuyers a potential break after a difficult September.
Discussion
Thoughts from readers and local market watchers.